
Semiconductor maker Penguin Solutions (NASDAQ:PENG) announced better-than-expected revenue in calendar Q3 2026 (fiscal Q4 2026), with sales up 67.7% year on year to $566.7 million. Its non-GAAP profit of $1 per share was 29.5% above analysts’ consensus estimates.
Is now the time to buy Penguin Solutions? Find out by accessing our full research report, it’s free.
Penguin Solutions (PENG) Q3 CY2026 Highlights:
- Revenue: $566.7 million vs analyst estimates of $521 million (67.7% year-on-year growth, 8.8% beat)
- Adjusted EPS: $1 vs analyst estimates of $0.77 (29.5% beat)
- Adjusted EBITDA: $93.27 million vs analyst estimates of $73.68 million (16.5% margin, 26.6% beat)
- Adjusted EPS guidance for the upcoming financial year 2027 is $4.45 at the midpoint, beating analyst estimates by 31.8%
- Operating Margin: 12.3%, up from 3.7% in the same quarter last year
- Free Cash Flow was -$167.4 million compared to -$73.36 million in the same quarter last year
- Inventory Days Outstanding: 166, up from 131 in the previous quarter
- Market Capitalization: $3.11 billion
Company Overview
Based in the US, Penguin Solutions (NASDAQ:PENG) is a diversified semiconductor company offering memory, digital, and LED products.
Revenue Growth
Examining a company’s long-term performance can provide clues about its quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Regrettably, Penguin Solutions’s sales grew at a mediocre 2.9% compounded annual growth rate over the last five years. This was below our standards and is a poor baseline for our analysis. Semiconductors are a cyclical industry, and long-term investors should be prepared for periods of high growth followed by periods of revenue contractions.
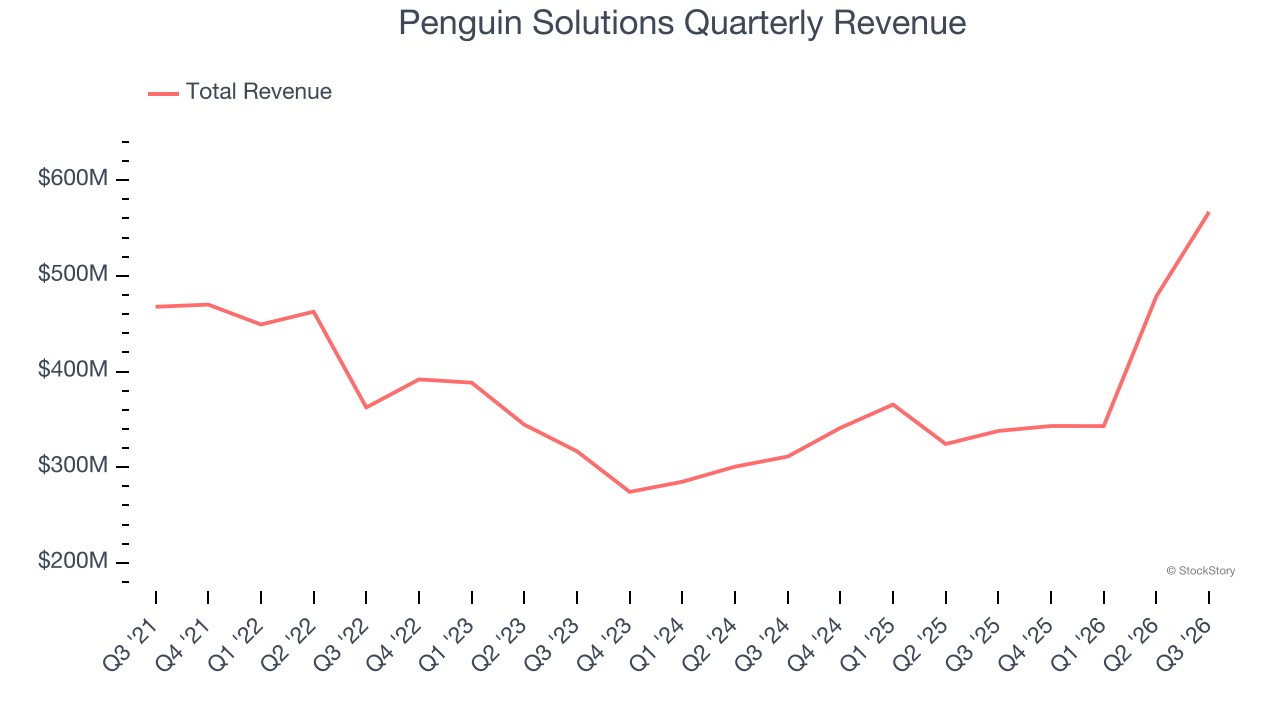
Long-term growth is the most important, but short-term results matter for semiconductors because the rapid pace of technological innovation (Moore’s Law) could make yesterday’s hit product obsolete today. Penguin Solutions’s annualized revenue growth of 21.6% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 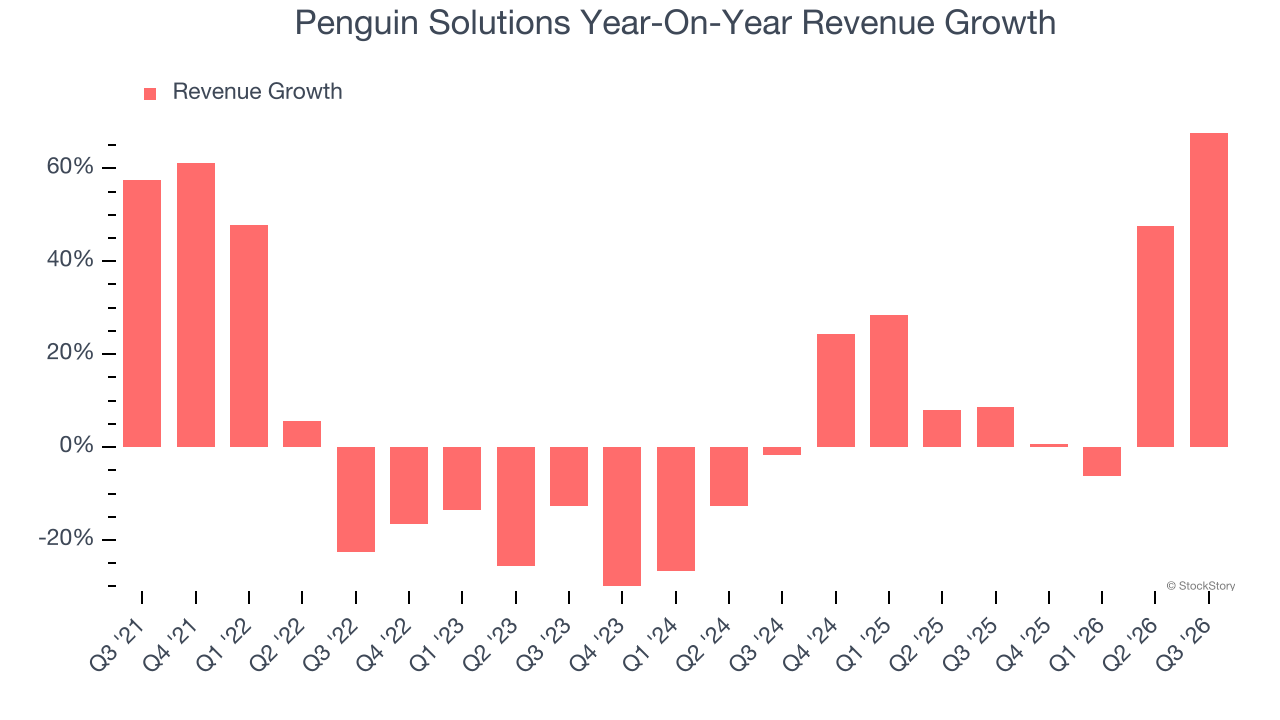
This quarter, Penguin Solutions reported magnificent year-on-year revenue growth of 67.7%, and its $566.7 million of revenue beat Wall Street’s estimates by 8.8%.
Looking ahead, sell-side analysts expect revenue to grow 27.8% over the next 12 months. Although this projection suggests its newer products and services will fuel better top-line performance, it is still below the sector average.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Product Demand & Outstanding Inventory
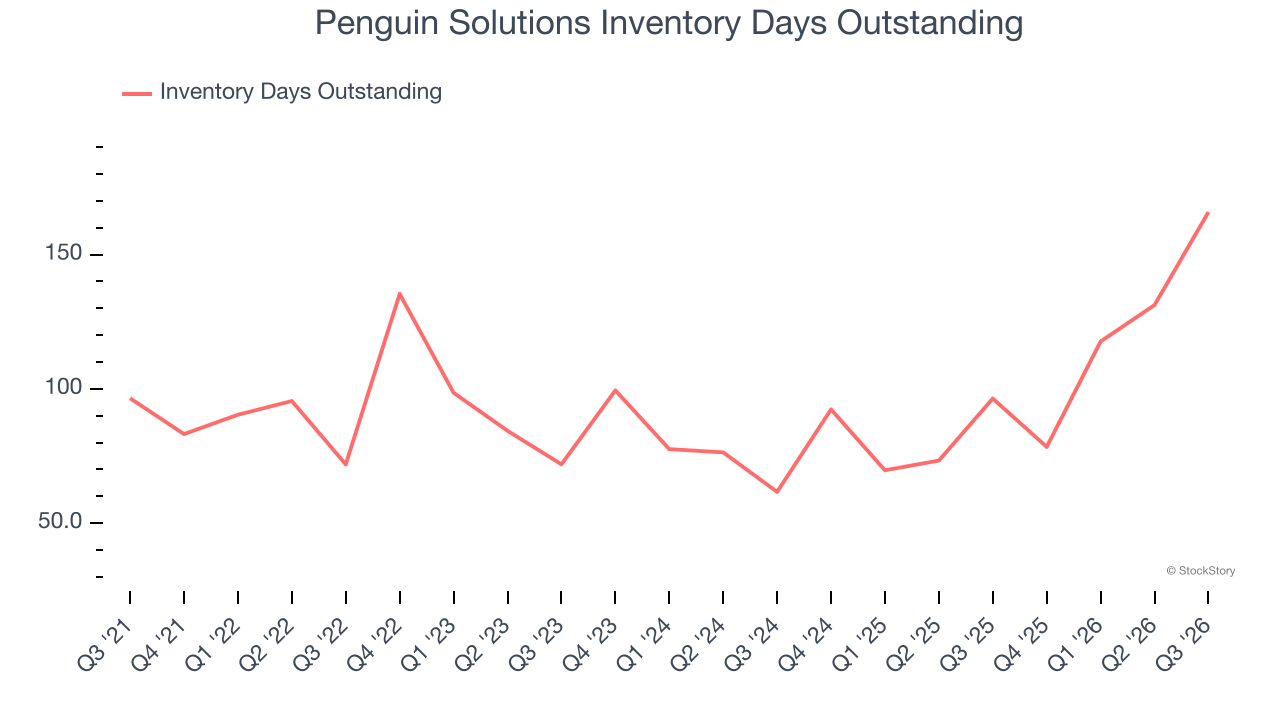
Days Inventory Outstanding (DIO) is an important metric for chipmakers, as it reflects a business’s capital intensity and the cyclical nature of semiconductor supply and demand. In a tight supply environment, inventories tend to be stable, allowing chipmakers to exert pricing power. Steadily increasing DIO can be a warning sign that demand is weak, and if inventories continue to rise, the company may have to downsize production.
This quarter, Penguin Solutions’s DIO came in at 166, which is 72 days above its five-year average, suggesting that the company’s inventory has grown to higher levels than we’ve seen in the past.
Key Takeaways from Penguin Solutions’s Q3 Results
It was good to see Penguin Solutions beat analysts’ EPS expectations this quarter. We were also excited its operating income outperformed Wall Street’s estimates by a wide margin. On the other hand, its inventory levels materially increased. Zooming out, we think this quarter featured some important positives. The stock traded up 2.4% to $66.27 immediately following the results.
Penguin Solutions may have had a good quarter, but does that mean you should invest right now? The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation, when deciding if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).